There is a program that hands qualified buyers up to $20,000 toward a home in certain Anaheim census tracts, with no income restrictions attached. Most people shopping in that price range have never heard of it.
That part is easy to write about. The part almost nobody explains is what happens next, because the grant arrives with a decision attached, and the decision turns out to be worth more than the money.
I have a listing that qualifies, so instead of talking in generalities I asked the lender to run real numbers on it. What came back was a five column comparison showing something buyers almost never get to see: the same $20,000, spent five different ways, on the same house.
Here is all of it, fees included.
First, what the grant actually is
It is not a seller credit, and it is not a price reduction. The seller's number does not move. This is a grant from the lender to the buyer, offered because of where the property sits, and there is nothing to pay back. No lien. No second payment sitting behind your mortgage. Nothing to refinance out of down the road.
The program is City National Bank's Welcome Home Grant. It is tied to federally designated census tracts, and when a property falls inside one, income limits come off entirely. That last piece matters more than people expect. Most down payment assistance in California caps household income somewhere uncomfortable. This does not.
It also arrives with three features that are unusual as a package:
- 3% down, so a $688,000 purchase needs $20,640 instead of the $137,600 a 20% buyer would bring
- No mortgage insurance at any down payment, which is the piece the lender himself called the standout
- Reduced origination fees
Stack those together and the barrier to buying stops being the down payment. It becomes the monthly payment, which is exactly where the real decision lives.
Step One
Is the address you are watching inside a qualifying tract?
Eligibility runs by address, not by neighborhood, so two homes four blocks apart can land on opposite sides of the line. Send me the addresses on your list and I will check every one of them against the map. It is a free question with a potentially $20,000 answer.
The house I ran it on
To keep this concrete rather than theoretical, every figure below is a real quote on a real listing: a renovated two bedroom, two bath loft at 435 W Center Street Promenade in Downtown Anaheim, offered at $688,000, with HOA dues of $540 a month.
Purchase price | $688,000 |
Down payment (3%) | $20,640 |
Loan amount | $667,360 |
Maximum loan to value | 97% |
Minimum credit score | 660 |
Property type | Condo |
Occupancy | Owner occupied |
Loan program | 30 year fixed |
Mortgage insurance | None required |
Rate lock | 120 days, one time float down |
Quoted August 12, 2026. Rates move daily, and this sheet already replaced one issued two days earlier at a slightly different base rate. Treat every number here as an illustration of how the math behaves, not as a rate you can call and get today.
One detail in that table deserves more attention than it usually gets. A 120 day lock with a one time float down means a buyer can lock now and still capture a drop once before closing. In a market moving the way this one is, that is a real piece of protection, and almost nobody brings it up.
The choice: cheapest to walk in, or cheapest to live in
The grant can be pointed in three directions. Toward your down payment. Toward closing costs and loan fees. Or toward discount points, which permanently lower your interest rate for the entire life of the loan.
Most buyers reach for the first option without pausing, and I understand the instinct. The down payment is the number standing between you and the house.
But watch what happens when the same $20,000 lands in different places.
Scenario | Rate | APR | Points paid | Principal & interest | Credit at closing | Cash to close* |
|---|---|---|---|---|---|---|
1 | 6.665% | 6.706% | $0 | $4,291 | $16,990 back | $3,650 |
2 | 6.540% | 6.619% | $2,669 | $4,236 | $14,378 back | $6,262 |
3 | 6.415% | 6.533% | $5,339 | $4,181 | $11,745 back | $8,895 |
4 | 6.290% | 6.445% | $8,008 | $4,126 | $9,091 back | $11,549 |
5 | 6.165% | 6.358% | $10,678 | $4,072 | $6,415 back | $14,225 |
*Down payment less the lender credit. Does not include prepaid taxes and insurance collected at closing, escrow setup, or third party costs such as title and recording. Ask your lender for a full Loan Estimate.
Look at the two ends of that table.
Scenario 1 puts none of the grant toward points. It covers the $3,010 in lender fees and hands back $16,990, which can go toward your down payment or prepaids. You walk into a $688,000 home with roughly $3,650 out of pocket toward the down payment, and your payment is $4,291.
Scenario 5 spends nearly all of it buying the rate down to 6.165%. You bring about $14,225 to closing, and your payment is $4,072.
Same house. Same grant. A $219 a month difference, and a $10,575 difference in what you need sitting in the bank.
Your Numbers, Not Mine
Which of those five columns is actually yours?
The table above is one price, one credit profile, one set of assumptions. Yours will look different. Tell me the price range you are shopping and roughly what you have set aside, and I will have the lender build this same five column comparison around your situation, usually the same day.
The number that should decide it
Here is the calculation almost nobody runs, and it is not complicated.
Scenario 5 costs $10,575 more up front than Scenario 1. It saves $219 every month.
$10,575 divided by $219 is 48 months.
Four years.
That is your break-even. Stay in the home longer than four years and the buydown was the better use of the money. Sell or refinance sooner and you would have been better off keeping the cash.
For scale on the other side of the ledger: hold that loan for the full term and $219 a month adds up to roughly $78,840 in interest you never pay.
So the honest advice is not "always buy the rate down." It is a pair of questions. How long are you actually going to be here, and how much cash is left in the account after closing? A buyer with reserves who plans to stay a decade should look hard at the right side of that table. A buyer who would be scraping the account empty to get there should not, because being house poor at a lower rate is still being house poor.
Fifteen Minutes
Let's find your break-even before you fall in love with a house
Bring me two things and this becomes a short conversation: how long you realistically expect to stay, and what you want left in savings the day after closing. Those two answers pick your column. Doing this before you write an offer is far easier than reworking it after.
What it really costs per month, all in
A principal and interest figure is not a housing payment, and comparing homes on P&I alone is how people end up surprised in month two. Here is the full monthly picture on this property.
Scenario 1 | Scenario 3 | Scenario 5 | |
|---|---|---|---|
Principal & interest | $4,291 | $4,181 | $4,072 |
Property taxes (est.) | $707 | $707 | $707 |
Homeowners insurance | $167 | $167 | $167 |
HOA dues | $540 | $540 | $540 |
Mortgage insurance | $0 | $0 | $0 |
Total monthly | $5,705 | $5,595 | $5,486 |
A few notes on those lines, because they are where estimates usually go sideways.
Property taxes
This is the line most buyers get wrong, and it is worth walking through slowly. The current owner’s 2025 tax bill on this unit was $5,107, because the county still assesses the property at $414,336 under Prop 13. You do not inherit that number. When you buy, the property is reassessed at what you paid, so your bill gets rebuilt on $688,000.
Run the real rate off that bill, $5,107 against a $414,336 assessment, and this tax rate area works out to roughly 1.23%. Applied to a $688,000 purchase, that is about $8,480 a year, or $707 a month. Search for Anaheim’s property tax rate and you will find something closer to 0.67%, which will mislead you badly. That is an effective rate averaged across all homeowners, most of them sitting on assessments set years ago.
Two things worth knowing beyond the number itself. I pulled the county assessment record on this unit and there is no Mello-Roos and no special assessment, which is not a given in Orange County and is worth verifying on every home you compare. And the rate here has been creeping up: 1.192% in 2023, 1.194% in 2024, 1.233% in 2025. Budget off the current year, not an old one.
HOA dues
At $540 in this building, this line is worth comparing seriously against other downtown options. A comparable listing nearby runs closer to $703. That gap is $163 a month, roughly $2,000 a year, and it stays completely invisible if you shop by list price alone.
Mortgage insurance
Zero, at 3% down. On a conventional loan at that down payment you would typically be looking at a few hundred dollars a month. Across the years it takes to reach 20% equity, that line alone is real money.
What is not in the table
Utilities, maintenance, and closing costs beyond the lender's own fees. Title, escrow, recording and prepaid impounds are separate, and your lender's Loan Estimate is where all of it shows up in one place.
Who actually qualifies
The restrictions are narrower than the headline suggests, and I would rather you know now than three weeks into a search.
- Owner occupied only. It has to be the home you live in. Not a rental, not a second home.
- You can only own one property. This is the one that catches people. If you are buying this and keeping your current place as a rental, you are out.
- 660 minimum credit score.
- 30 year fixed.
- The property has to sit in a qualifying census tract. Eligibility is by address, so two homes a few blocks apart can land differently.
- Financing has to go through City National Bank. It is a proprietary program. A buyer who brings their own lender does not get it, no matter how well they qualify.
That last one is worth repeating, because it is exactly where the money quietly disappears. Buyers fall in love with a home, get pre-approved wherever they always planned to, and never find out the grant existed.
Before You Get Pre-Approved
Read that list and think you might qualify? Say so now, not later
The single most expensive mistake here is timing. Once you are pre-approved somewhere else and under contract, the grant is gone. A five minute conversation before you pick a lender is what protects it. I can introduce you directly and stay in the middle so nothing falls through the cracks.
My take
The most interesting thing on that five column sheet is not the $20,000. It is that where you point the money matters more than the amount of it.
I watch buyers negotiate hard for a price reduction, then take a grant or a credit and drop it straight into the down payment without a second thought, because the down payment is the number that feels urgent. Meanwhile the payment they will carry for the next decade gets decided by default.
Neither answer is universally right. But it should be a decision made with a break-even sitting in front of you, and not a reflex.
If you are shopping in Anaheim and you have not asked whether the addresses on your list fall inside a qualifying tract, that is a free question with a potentially $20,000 answer.
The listing this was run on
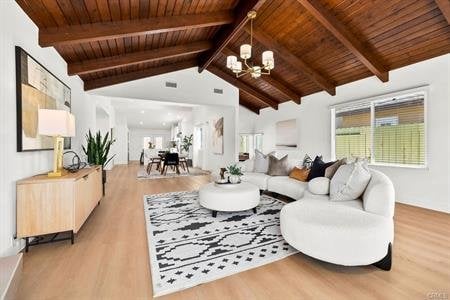
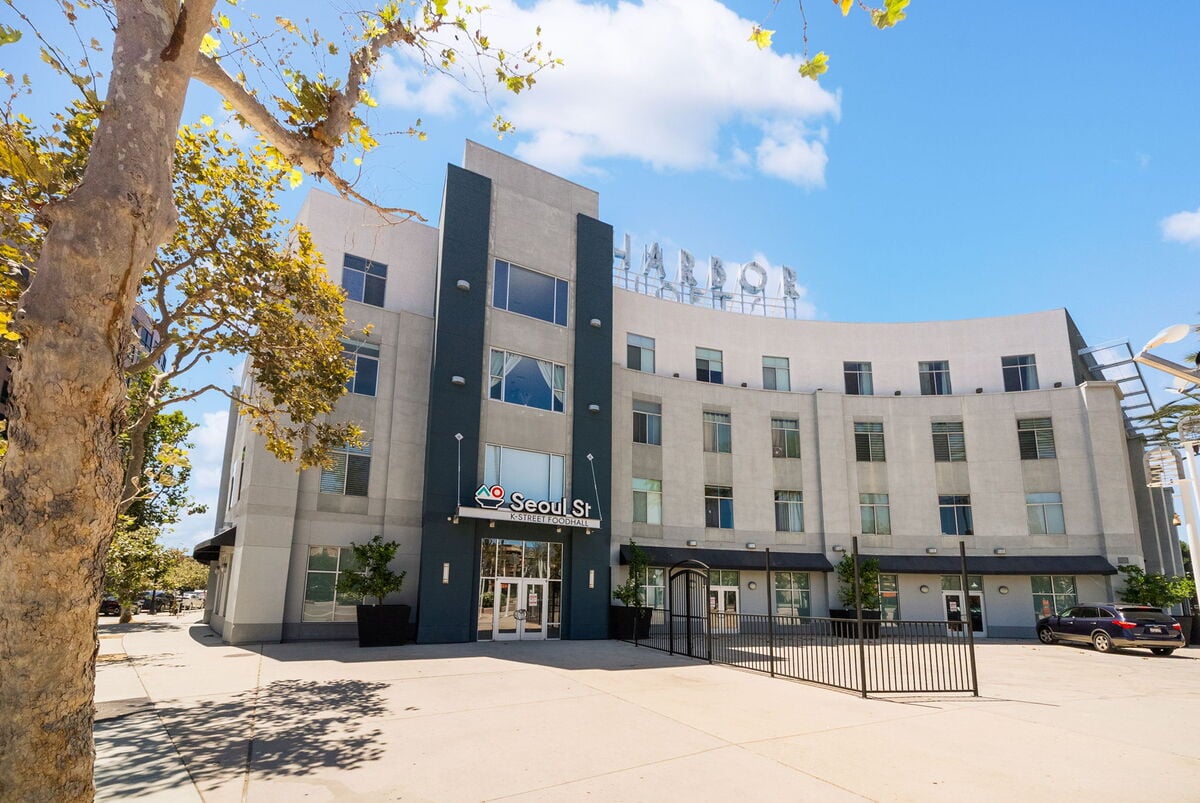
435 W Center Street Promenade #221, Anaheim. Two bedrooms, two baths, roughly 1,083 square feet, renovated and single level, with two assigned gated parking spaces and EV charging. The $540 HOA dues cover the pool, spa, fitness center, outdoor kitchen and controlled access. Offered at $688,000, sitting on the Center Street Promenade a short walk from the Packing House and The Rinks.
See the home
Photos, floor plan and the full listing site
Everything on this page is about the financing. If you want the home itself, the listing site has the full photo gallery, the floor plan, the neighborhood map, and a form to book a walkthrough.
Whenever You Are Ready
Want these numbers run on your own situation?
Everything above is an illustration built on one property and one credit profile. Yours will differ, sometimes by a lot. Send me the price range, the addresses you are watching, or just a question, and I will get you a real scenario from the lender rather than a rule of thumb. If you would like to see the loft in person, tours are by appointment and I can usually work around your schedule the same week.
Real Estate
Jade Larney
Anvil Real Estate · DRE 02241676
(949) 995-JADE / 5233 · [email protected] · jadelarney.com
Financing
Anthony Musante
Senior Loan Officer · City National Bank / RBC U.S. Mortgage · NMLS #632970
800.511.2151 · [email protected]
Anthony runs the Welcome Home Grant program at City National and built the five scenarios above. The email buttons on this page copy him automatically, so you get the financing answer and the real estate answer in one thread instead of two.
This is general real estate education, not lending, legal, or tax advice. All figures are estimates based on a lender quote dated August 12, 2026, for a $688,000 purchase with a $20,640 down payment (3%) and a $667,360 loan over 360 monthly payments, at the annual percentage rates shown. Rates, terms and program availability are set by the lender and change without notice. Property tax and insurance figures are estimates and will differ for your situation. The Welcome Home Grant is a program of City National Bank, a subsidiary of Royal Bank of Canada. Jade Larney and Anvil Real Estate are not the lender, do not originate mortgage loans, and are not affiliated with City National Bank. Not a commitment to lend. All loans subject to credit and property approval. Not all applicants will qualify. Equal Housing Opportunity. Equal Housing Lender. Anthony Musante, Senior Loan Officer, City National Bank, NMLS #632970; City National Bank NMLSR ID #536994. City National Bank is a subsidiary of Royal Bank of Canada. Confirm your specific situation with a qualified lender, CPA, or advisor before making a decision.